The D&O Diary’s busy fall travel schedule continued with back-to-back visits to Toronto and New York City, where I participated in a PLUS panel, led an educational session for The Bridge, and delivered a guest lecture at Columbia University.

PLUS Canada
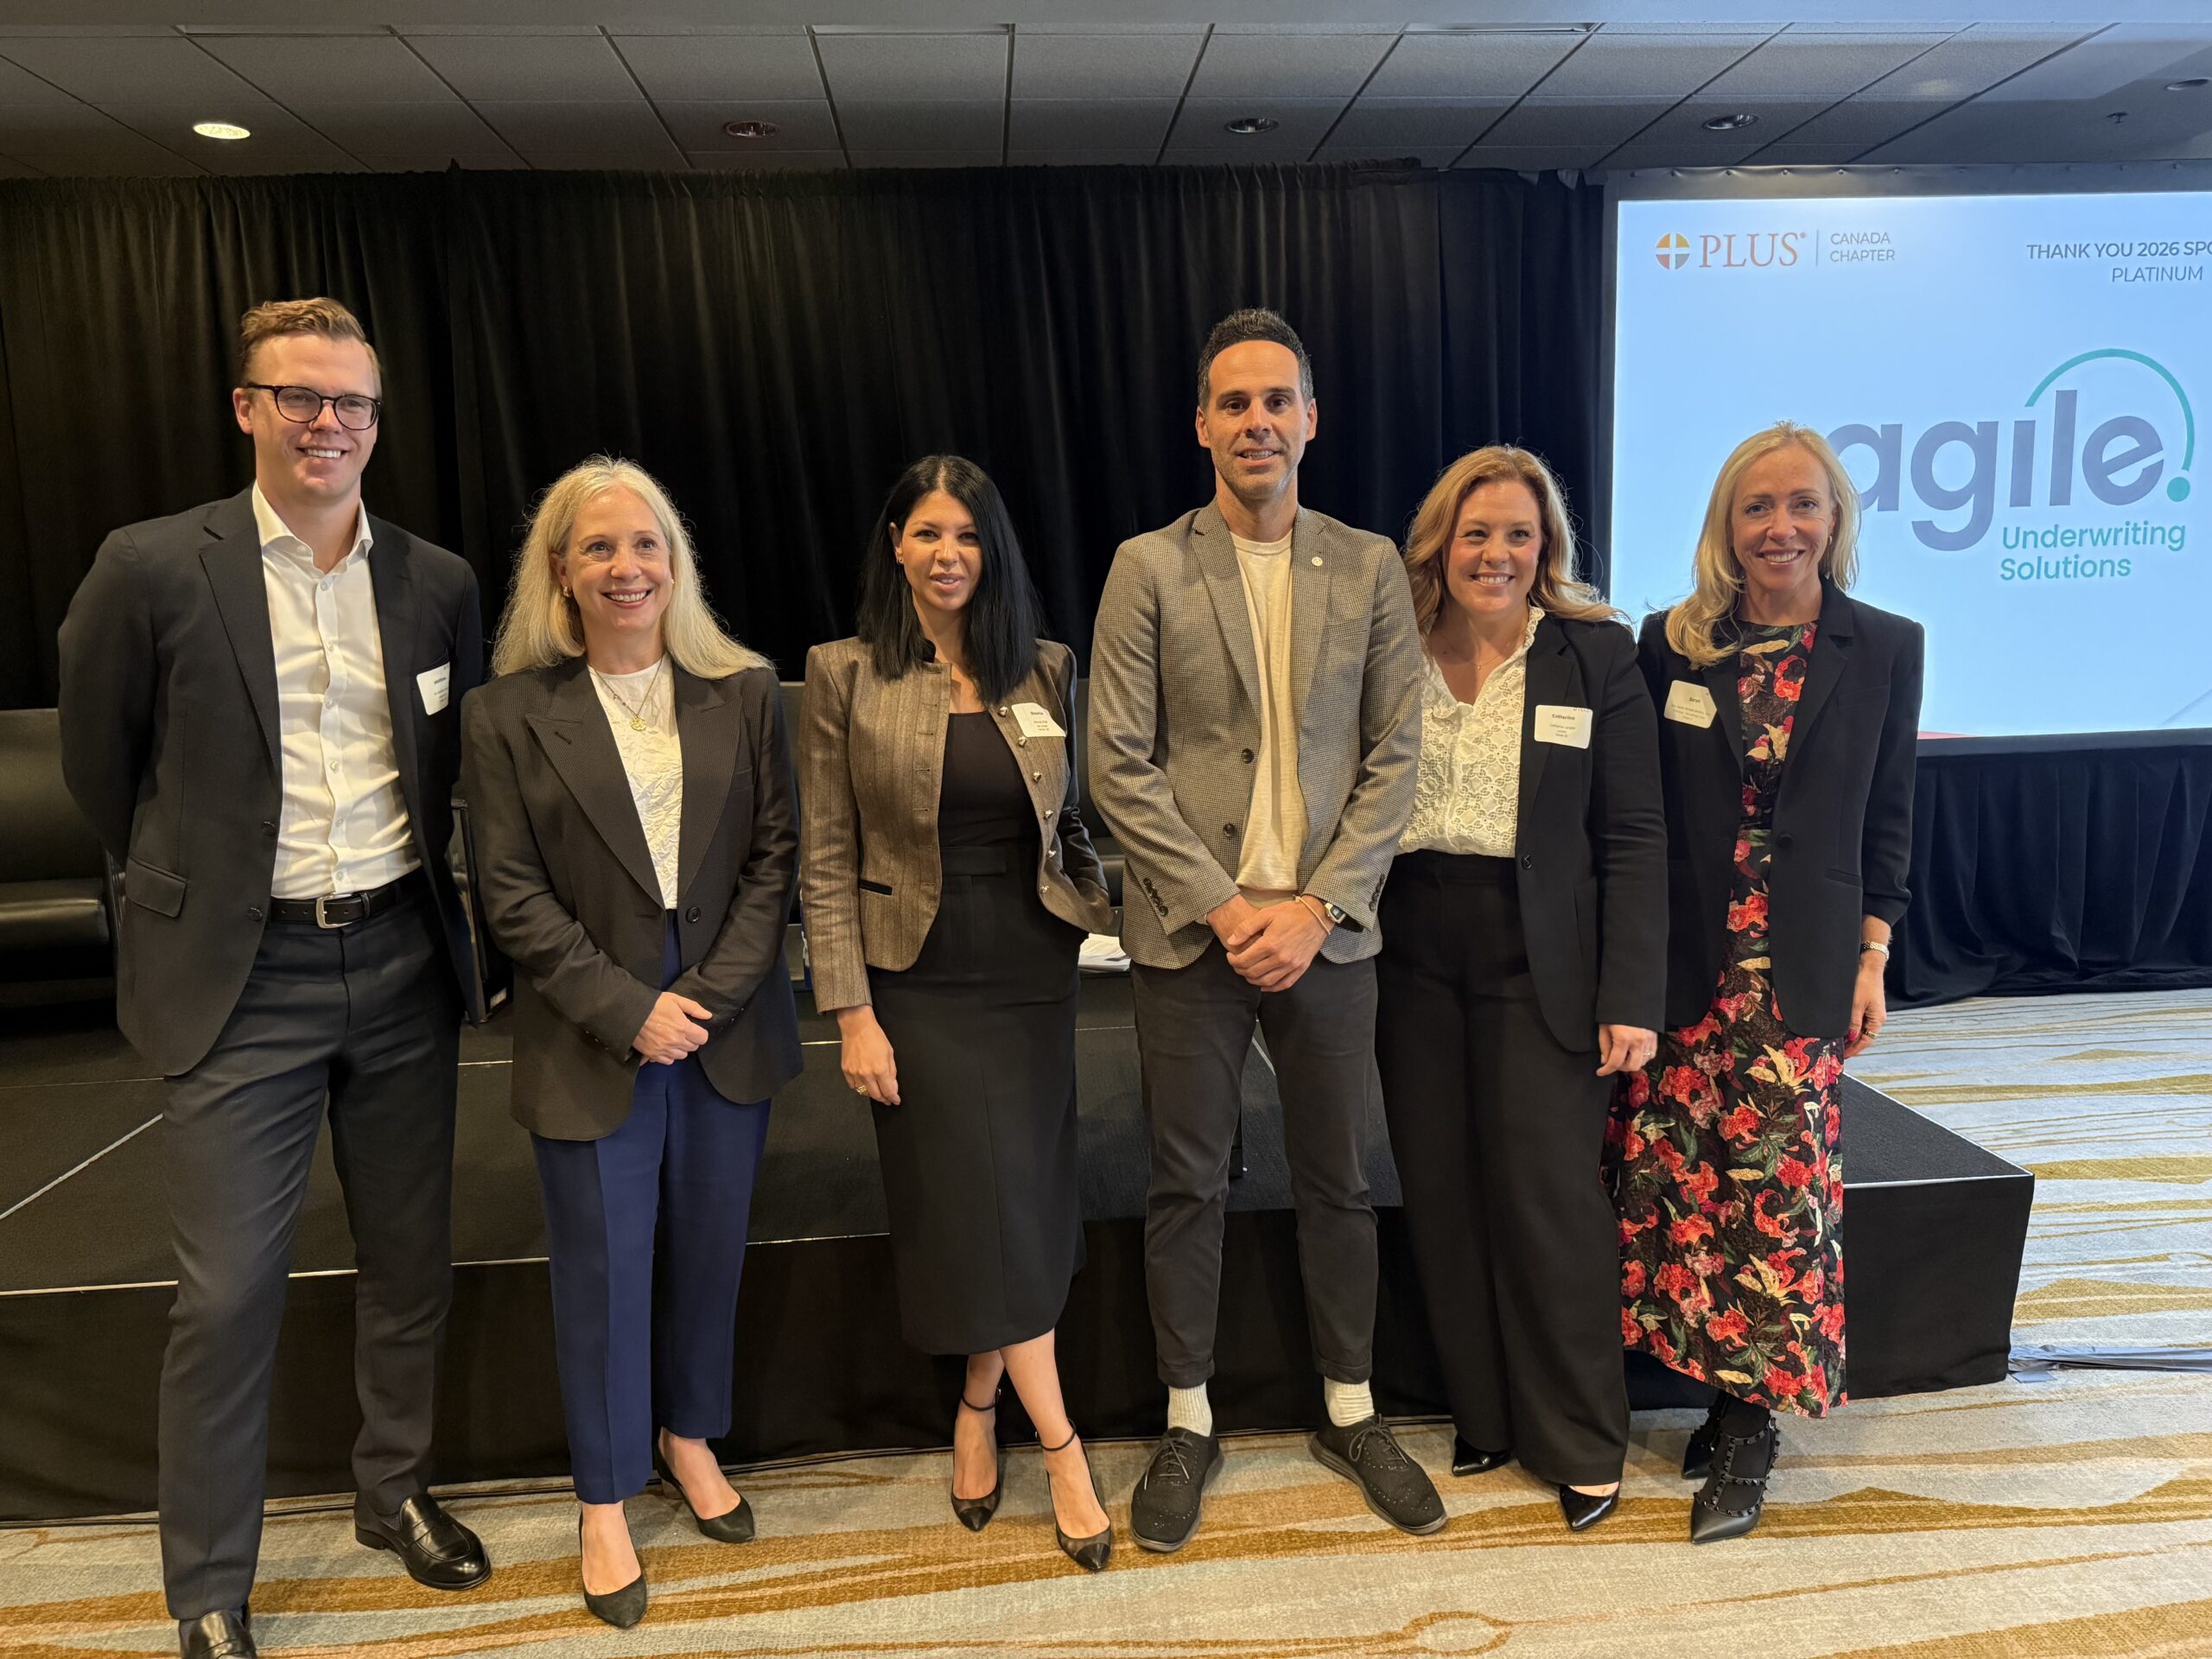
With fellow panelists Matthew Mann, Alison Penney, Dounia Khali, Philippe Côté, and Catherine Lanctôt

On October 1, I traveled to Toronto at the invitation of Nicole McAuley of Fasken Martineau DuMoulin LLP, to participate in the sold-out Canadian chapter of Professional Liability Underwriting Society (PLUS) event, “Inside Today’s D&O Market: Reinsurer Insights, Client Demands and Claims Trends.”

The panel was moderated by Philippe Côté, Senior Vice-President and National Practice Leader, Executive Risks, at BFL CANADA. Joining me on the panel were Dounia Khali, Senior Vice President, Financial Services Group, Aon; Catherine Lanctôt, Executive Vice President and National ProExec Leader, Lockton Canada; Alison Penney, Senior Vice President, Canadian Product Manager North American Financial Lines Chubb Insurance; and Matthew Mann, Senior Vice President, Gallagher Re.
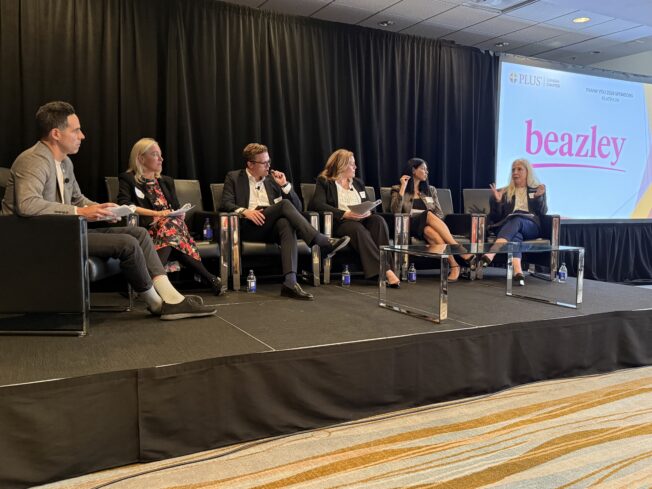
Artificial intelligence was a central topic. We discussed the growing wave of AI-related securities litigation and how AI-related D&O exposure increasingly arises from governance, disclosure, and oversight issues rather than the technology itself. We also discussed how AI-related securities litigation is being closely monitored from a reinsurance perspective, though any meaningful impact on the reinsurance market would likely require a broader impact to multiple coverage verticals.
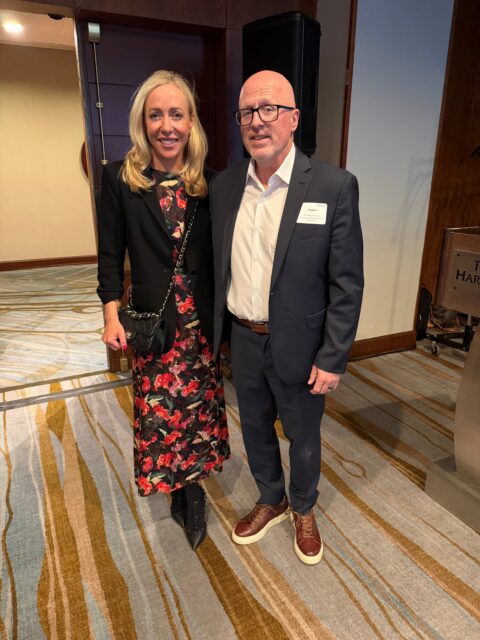
With Robbie Thompson, CEO of PLUS

Finally, we addressed several uniquely Canadian issues, including recent developments in Canadian securities litigation.

My thanks to Philippe, Dounia, Catherine, Alison, and Matthew for an engaging and thought-provoking discussion; to PLUS CEO Robbie Thompson for his support; and to the Canadian PLUS chapter organizers for bringing together such a knowledgeable group of industry professionals.

NYC

The Bridge Transcends

On October 6, I participated in a virtual educational session hosted by the Boston Chapter of The Bridge, an inclusive not-for-profit networking organization that supports the development of female talent in Financial Lines insurance and reinsurance.

The discussion focused on current securities litigation trends, several of the topics featured in The D&O Diary’s “What to Watch” discussions, including ways artificial intelligence continues to impact D&O liability and insurance. We also discussed my career journey, the role mentorship has played throughout my professional development.

My sincere thanks to Mary Coughlin, Managing Director and Head of Strategy & Execution, FINEX Commercial North America at WTW (Willis), and Eileen Purcell of Travelers for inviting me to speak. I am also grateful for their efforts in organizing the virtual event and in-person watch party and for serving as moderators of the discussion.

The Bridge Boston In-Person Watch Party Attendees with organizers Mary Coughlin and Eileen Purcell

Columbia University Guest Lecture

The next day, I guest lectured at Columbia University on the evolving NIL landscape and the management liability challenges facing universities and athletic departments in the post-House settlement environment. The presentation examined the growing centralization of NIL oversight within universities, along with the resulting governance, D&O, professional liability, and employment practices exposures, as well as recent legislative and regulatory developments.

Columbia University Library

As always, the discussion benefited from a highly engaged and knowledgeable group of students, many of whom have prior experience working in various segments of the sports industry.

I am grateful to Carla Varriale-Barker, Partner, and Courtney E. Dunn, Associate, both of Segal McCambridge Singer & Mahoney, for once again inviting me to speak to their Columbia University Sports Management and Law class.

With Courtney Dunn and the Columbia University Sports Management and Law Class

The D&O Diary has been closely following the rise in securities class actions filed in 2026 stemming from alleged market manipulation. A recently filed securities class action lawsuit against Datavault AI Inc. arises from what plaintiffs characterize as a stock-promotion campaign built around artificial intelligence, blockchain technology, quantum computing, and data-monetization opportunities. Formerly known as WiSA Technologies, Inc., the company rebranded following its acquisition of intellectual-property assets from Data Vault Holdings Inc. and promoted a business model centered on data exchanges, high-performance computing, and technology licensing.

The September 25, 2026, complaint also builds upon allegations asserted in a securities suit filed against the company a month earlier by extending the class period, adding additional corrective disclosures, and incorporating allegations concerning liquidity, financing activities, and going-concern issues. As discussed below, the Datavault AI lawsuit underscores how D&O exposure can emerge when optimistic statements about growth prospects and financing opportunities are later followed by disclosures concerning liquidity challenges and financial performance.

Continue Reading Datavault AI Hit with Market-Manipulation-Related Securities Suit

The overall number of Delaware Chancery Court M&A lawsuit settlements increased in 2025, but aggregate, average, and median settlement values decreased during the year, according to a new report from Cornerstone Research. The report, which is entitled “M&A Litigation Settlements in the Delaware Court of Chancery: 2012-2025 Review & Analysis,” attributes the 2025 declines in settlement values to the number of SPAC merger-related lawsuit settlements during the year. Cornerstone Research’s September 23, 2026, press release about the report can be found here. The report itself can be found here.

Continue Reading Del. Chancery Court M&A Lawsuit Settlement Values Decreased in 2025

As we have detailed in prior posts (most recently here), one of the key securities class action litigation filing trends this year has been the emergence of a host of securities suits alleging various types of market manipulation, including, in particular pump-and-dump schemes. In the latest example of this trend, on September 10, 2026, a plaintiff shareholder filed a securities lawsuit against the Singapore-based Ryde Group (RYDE) in a complaint alleging that the defendants engaged in a pump and dump scheme. This new lawsuit is the 15th market manipulation complaint to be filed so far this year.

Continue Reading New Market Manipulation-Related Securities Suit Filed Against Ryde Group
Singapore

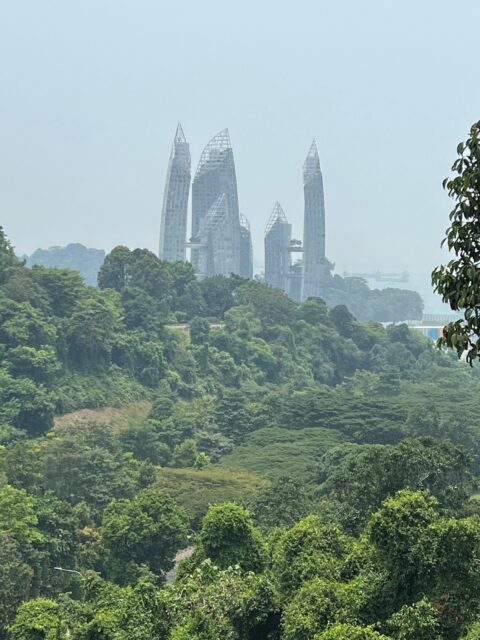
This past week, I was on assignment for The D&O Diary in Singapore, the prosperous and verdant city-state in equatorial Southeast Asia. With its clean and orderly streets and its lush parks, as well as its fabulous food scene, Singapore is one of my favorite places to visit, and this return trip reconfirmed my appreciation for the place.

Continue Reading Singapore

Michael W. Peregrine and Nathan Barnett

In the following guest post, Michael W. Peregrine and Nathan Barnett examine a recent Delaware Chancery Court decision dismissing oversight claims against Boeing directors arising from the January 2024 mid-air door-plug incident. As they explain, the decision provides important guidance on the continuing application of the Delaware courts’ Caremark doctrine, reaffirming that bad faith remains the essential prerequisite for oversight liability, clarifying the distinction between compliance risks and business risks, and offering additional insight into what constitutes a true “red flag” for board oversight purposes. The authors also discuss the practical governance lessons boards can draw from the decision and the importance of maintaining a robust compliance framework. Michael Peregrine is a retired lawyer and a fellow of the American College of Governance Counsel, and Nathan Barnett is a partner with McDermott, Will &Schulte LLP. Our thanks to Michael and Nathan for allowing us to publish their article on our site.

Continue Reading Guest Post: New Caremark Decision Provides Good News About Bad Faith

The U.S. IPO market has continued its strong resurgence in 2026. According to the latest IPO statistics compiled by Benjamin P. Edwards, Associate Dean for Faculty Development and Research and Professor of Law at the William S. Boyd School of Law at the University of Nevada, Las Vegas (UNLV), and his research team, IPO activity through August reflects a robust issuance environment featuring a mix of traditional operating company IPOs, direct listings, and a surprisingly strong return of SPAC offerings.

The SPAC resurgence is particularly noteworthy because it follows a period in which many de-SPAC companies struggled to meet the optimistic projections that helped fuel the prior SPAC boom. And, while sponsors are once again launching blank-check companies, courts continue to issue significant rulings arising from de-SPAC transactions completed during the 2020-2021 SPAC boom.

Continue Reading IPO Activity Roars Back While SPAC Litigation’s Long Tail Continues

As we have noted on this site in recent years, privacy-related issues have been and remain a significant potential source of D&O risk and liability exposure. In the latest example of the ways that privacy-related concerns can translate into D&O claims, a plaintiff shareholder has filed a shareholder derivative lawsuit against the board and controlling shareholders of company Alphabet alleging that the defendants violated their fiduciary duties by failing to take steps to protect the company from over $4.5 billion in fines, penalties, and settlements arising from alleged privacy violations. A copy of the redacted public version of the September 22, 2026, complaint can be found here.

Continue Reading Alphabet Board Hit with Privacy-Related Follow-On Derivative Lawsuit

As the 2026 proxy season recedes into the rearview mirror, several clear themes have emerged. Perhaps the most notable is that, despite years of intense focus on environmental and social issues, shareholder attention has increasingly returned to traditional governance concerns. Governance proposals not only proved more resilient than other proposal categories, but they also received some of the strongest levels of investor support.

The level of backing these proposals received indicates that investors continue to place a premium on board oversight, accountability, and governance frameworks as the first line of defense against emerging risks. At the same time, investors are demonstrating a growing interest in how boards oversee artificial intelligence, reflecting the reality that AI has become both a business opportunity a potential source of operational, regulatory, and litigation risk.

These developments are unfolding against a rapidly changing regulatory backdrop. During the 2026 proxy season, the SEC significantly reduced its traditional involvement in the Rule 14a-8 no-action process, leaving issuers with greater responsibility for shareholder proposal exclusion decisions. Meanwhile, the agency has reportedly begun considering rescission of Rule 14a-8 altogether, a move that could shift primary responsibility for shareholder proposal matters back to state law.

As discussed in more detail below, these governance trends and changes in the shareholder proposal landscape suggest that board oversight and accountability, particularly with respect to AI, may become increasingly important indicators of D&O risk.

2026 Proxy Season

Several recently published reviews of the 2026 proxy season reveal a consistent pattern regarding investor priorities.

According to ISS-Corporate, overall shareholder proposal volume fell to a five-year low, but governance proposals proved remarkably resilient. Governance proposals increased in relative prominence, received the highest average shareholder support (31.4%), and were the only proposal category to consistently receive majority approval. D.F. King’s proxy season review reached a similar conclusion, noting that governance proposals accounted for an increasing number of shareholder proposal activity and most majority-supported proposals.

That governance focus is especially evident in the area of artificial intelligence. An ISS STOXX study of more than 3,000 Russell 3000 and S&P 500 companies found that only 8% disclosed board-level AI oversight, 9% disclosed formal AI governance policies, and 16% reported having at least one director with AI expertise, indicating that AI adoption is significantly outpacing AI governance. At the same time, EY reported growing investor demand for transparency around AI oversight and board expertise, noting that 37% of S&P 500 companies now disclose AI-related experience for at least one director, up from 11% in 2022.

Discussion

One of the more important takeaways from the 2026 proxy season is how investors increasingly view governance as the mechanism through which boards should oversee emerging risks. The growing focus on AI oversight reflects an expectation that boards establish governance structures around technology that present significant strategic, regulatory, and litigation risks.

That development is particularly noteworthy considering the significant rise in AI-related D&O claims. 24 AI-related federal securities class action lawsuits have been filed through September 28, 2026, compared to 16 during all of 2025, making AI-related litigation one of the most significant D&O claims trends of the year. The allegations have expanded well beyond traditional “AI-washing” claims and now include issues involving disclosure controls, infrastructure investments, competitive positioning, business disruption, and board oversight.

For D&O underwriters, the proxy season results may provide an early indication of where future scrutiny and litigation risk may emerge. While traditional governance indicators remain important, the increased investor focus on AI oversight suggests that governance surrounding emerging technologies may become an increasingly relevant indicator of D&O risk.

Underwriters may therefore want to evaluate whether boards have clearly assigned responsibility for AI oversight, adopted formal governance policies, developed relevant expertise, and implemented disclosure controls around AI-related statements and projections. Notably, these are the same issues attracting attention from both investors and plaintiffs’ lawyers. As a number of guest authors on The D&O Diary have recently observed, effective AI governance requires clear oversight, board engagement, relevant expertise, and disciplined disclosure practices. The proxy season data suggests investors have reached the same conclusion.

Companies that aggressively promote AI opportunities while providing limited evidence of board-level oversight may present a different risk profile than companies with more mature governance frameworks. That distinction may become increasingly relevant as AI-related litigation and regulatory scrutiny continue to evolve, particularly given the ISS STOXX finding that relatively few companies currently disclose formal AI oversight structures or governance policies.

At the same time investors are demanding stronger board oversight of emerging risks such as AI, the regulatory framework governing how shareholders express those concerns through the proxy process is also evolving.

The significance of the SEC’s evolving Rule 14a-8 approach extends beyond shareholder proposal mechanics. For decades, Rule 14a-8 has served as the primary mechanism through which shareholders raise governance concerns and seek board accountability through the proxy process. As SEC staff involvement in no-action determinations declines, proposal volume and ballot outcomes may become less reliable indicators of investor priorities. Accordingly, the decline in shareholder proposals during the 2026 proxy season should not necessarily be interpreted as diminished investor concern. Rather, investors may increasingly pursue governance objectives through engagement, director elections, activist campaigns, or litigation. This distinction is important because the season’s strong support for governance proposals suggests that governance remains central to investor expectations, even as the mechanisms for expressing those expectations evolve.

For D&O underwriters, the key implication is that governance concerns may become more important than proposal statistics themselves. Indeed, the 2026 proxy season suggests investors remain highly focused on board accountability, risk oversight, and governance structures, particularly with respect to AI. Even if proposal activity declines as a result of regulatory changes, investor concerns are unlikely to disappear and may instead manifest through engagement, voting pressure, activism, or litigation.

As a result, underwriters may increasingly benefit from evaluating the substance of a company’s governance framework rather than relying solely on traditional proxy season metrics. For emerging risks such as AI, governance quality may become a useful proxy for future D&O risk.

My overseas assignment for The D&O Diary continued this week with a stop in the Catalan city of Barcelona, nestled between the mountains and the sea in coastal Spain. I was very happy to be back in Barcelona again, because I know from prior experience that the city’s combination of great weather, splendid setting, excellent food, and architectural richness is pretty hard to beat.

Continue Reading Barcelona